

Insurance Matching Laws After a Fire: Cabinets, Flooring and Siding That No Longer Match

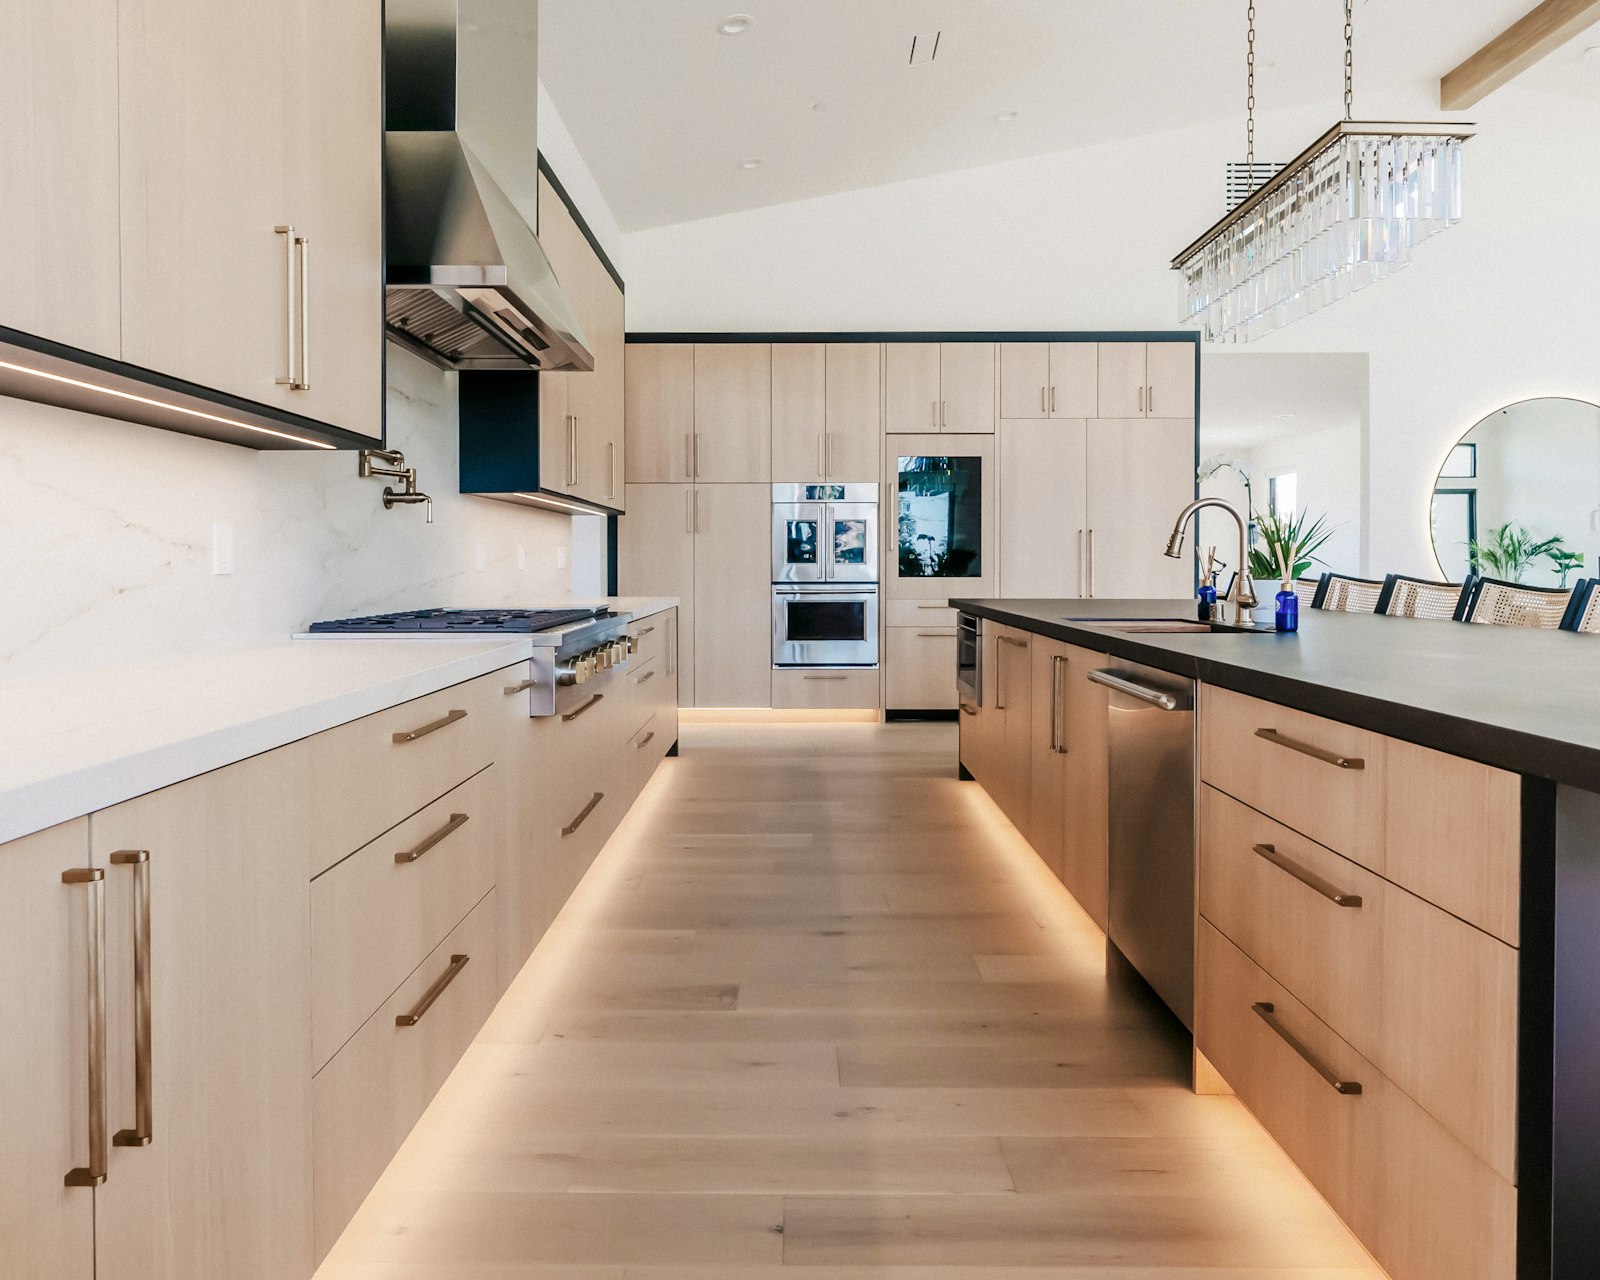
A fire destroys half the kitchen cabinets. The insurer agrees to replace the burned ones, but the same style is no longer made, and the new cabinets will sit next to old ones in a different finish. Or the fire melts vinyl siding on one wall, and the replacement color does not match the other three. Insurance matching laws exist for exactly this problem.
The matching problem
Homeowners policies promise to repair or replace damaged property with material of like kind and quality. They usually do not say anything about undamaged property next to it. Insurers often argue they only owe for what was physically damaged. Policyholders argue that a repair that leaves a visible mismatch does not restore the home to its pre-loss condition.
What matching laws say
The National Association of Insurance Commissioners (NAIC) model regulation on unfair property claim practices addresses this directly. It says that when replaced items do not match in quality, color or size, the insurer should replace all such items in the area so the result has a reasonably uniform appearance.
Several states have adopted some version of that rule. Among the states ClaimWarriors serves:
- California requires replacement of all items in the damaged area so they conform to a reasonably uniform appearance.
- Connecticut has a matching statute that applies to both interior and exterior losses.
- Nebraska and Utah have adopted matching regulations based on the NAIC model.
Other states rely on case law and the policy's own wording. Some insurers now add endorsements that limit matching. Check your policy for any matching or cosmetic damage language.
What "reasonably uniform" means
It does not require a perfect match. A California court has said a perfect match is not required. It does mean that a visible, obvious mismatch in the same area is not acceptable. Disputes usually turn on:
- What counts as "the area": one wall, one room, the whole kitchen, or everything visible from one spot (a "line of sight" test some states use).
- Whether a match is available: if matching material can be found, partial replacement may be enough.
- Continuous materials: flooring that runs through several rooms without a break, or siding that wraps the whole house.
Common fire-related matching disputes
- Kitchen cabinets where only some boxes burned or were smoke-damaged.
- Hardwood or tile flooring that runs continuously from a damaged room into undamaged ones.
- Vinyl siding melted on one elevation, where the color has faded or been discontinued.
- Countertops with a seam between damaged and undamaged sections.
- Roofing partly burned or damaged by firefighting.
How to document a matching claim
- Get proof the material is unavailable. A supplier letter or manufacturer notice that the product is discontinued is strong evidence.
- Photograph the transition. Show how the new and old would sit side by side, from normal viewing positions.
- Show continuity. For flooring, photograph that it runs without a break between rooms.
- Cite your state's rule if it has one, in writing.
- Ask for a sample. Have the contractor bring the closest available match and photograph it against the existing material.
If the insurer refuses
Ask for a written explanation with the policy language and any state rule it is relying on. If the disagreement is about how much needs replacing, the appraisal clause may resolve it. See insurance appraisal in a fire claim. If you believe the insurer is ignoring a clear state rule, a complaint to your state insurance department is another option.
Matching disputes often show up as a gap between the insurer's estimate and your contractor's bid. See how to counter a lowball fire offer and how to deal with the adjuster after a house fire.
How other states word the rule
- Ohio requires repairs or replacement that give a reasonably comparable appearance.
- Iowa looks at whether the mismatch is within the line of sight.
- Kentucky, Rhode Island and Florida have their own matching rules.
The wording matters. A rule tied to "the area" can lead to a different result than one tied to line of sight.
Cabinets: an illustrative example
These numbers are for illustration only. A kitchen has 20 cabinet boxes in one continuous run. A fire burns 8 of them and smoke stains the rest. The style was discontinued. The insurer offers to replace the 8 burned boxes with the closest available style and clean the other 12. The homeowner shows that no matching doors or finish are available and that the new boxes would sit in the same run as the old ones. Under a rule like California's, that supports replacing all 20 so the kitchen has a reasonably uniform look.
What a contractor statement should cover
- The exact product, color and size of the existing material.
- Whether the product is still made, with a supplier or manufacturer source.
- The closest current match and how it differs.
- Whether old and new material can be separated by a natural break, such as a doorway.
- The cost to replace the full area.
A specific statement carries more weight with an adjuster than a general opinion that it will not match.
Common questions
Does insurance have to match my cabinets after a fire?
Many states require insurers to replace enough items to achieve a reasonably uniform appearance when repaired areas cannot match. Rules vary by state and policy.
Which states have matching laws?
Several states have regulations or court decisions on matching, and they differ in detail. Check your state's insurance regulations or ask your insurer in writing how it handles matching.
What evidence helps a matching claim?
Photos showing the mismatch, product discontinuation notices and contractor statements. Include it in a written supplement. See claim supplements.
Does Rhode Island have a matching rule?
Yes, Rhode Island has adopted a matching rule in some form. Check the current regulation and your policy wording.
Does matching apply to siding and roofs?
Often. Connecticut's statute covers both interior and exterior losses. Other states apply their rule to the damaged area or the line of sight, which can include exterior surfaces.
Help with matching disputes
ClaimWarriors documents matching issues and presses for a uniform repair. See our fire claim services, or contact us for a claim review.
This article is general information about property insurance claims, not legal advice. Matching rules vary by state and policy. Last reviewed November 2026.




