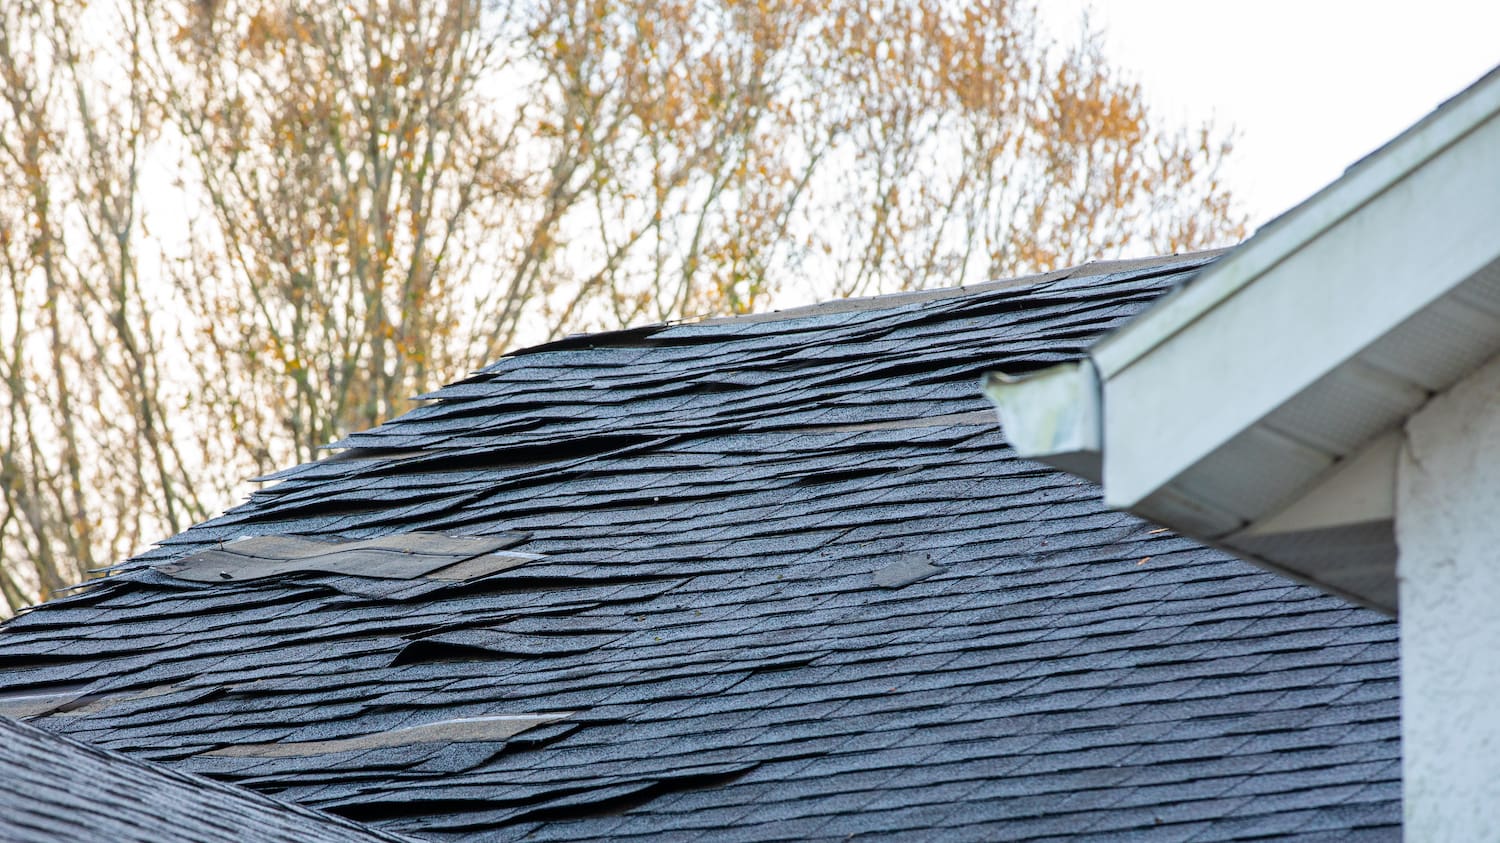
How Much Does Insurance Pay for Roof Replacement?


How much does insurance pay for roof replacement? For a covered loss, it pays the cost to replace the roof minus your deductible, but the timing and the final amount depend on your loss settlement terms. With replacement cost coverage, you get actual cash value first and the withheld depreciation after the roof is replaced. With an actual cash value roof endorsement, the depreciation is never paid. With a roof payment schedule, you get a set percentage based on the roof's age and material. A percentage wind and hail deductible can take a large bite out of any of them.
This guide shows how a roof payout is calculated, what goes into a complete roof estimate, and why roof checks can come in lower than the roofer's bid. Whether a full roof is owed at all is covered in does homeowners insurance cover roof replacement.
The basic formula
Start with the replacement cost: what it costs today to remove the old roof and install a new one of like kind and quality. Then:
- Subtract depreciation if the insurer is paying actual cash value first.
- Subtract your deductible. If your policy has a separate wind and hail deductible, that one applies to storm roof claims.
- Apply any roof schedule or actual cash value endorsement in your policy.
- Add the withheld depreciation later, if your policy allows it and you replace the roof.
The standard ISO form, HO 00 03, pays no more than actual cash value until the repair or replacement is complete, and requires you to notify the insurer within 180 days after the loss that you intend to replace, to keep your right to the rest.
Three ways a roof can be paid
Replacement cost
The full cost of the new roof, paid in two parts. The first check is replacement cost minus depreciation and deductible. The second is the depreciation, released once the roof is done. See roof depreciation in an insurance claim.
Actual cash value only
ISO's HO 04 93 endorsement and similar carrier forms pay wind and hail losses to roof surfacing at actual cash value, with no second check. The older the roof, the bigger the gap between the payment and the cost of a new roof.
Roof payment schedule
Some policies pay a fixed percentage of the roof's replacement cost based on its age and material. ISO's HO 06 46 endorsement uses a percentage table. Some insurers file their own. The Missouri Department of Insurance publishes how individual insurers settle roof claims, including optional schedules that lower the premium.
The deductible can be larger than you think
Policies in hail-prone states can have a separate wind and hail deductible stated as a percentage of the dwelling coverage. The Colorado Division of Insurance gives 1%, 2% or 5% as examples. On a home insured for $450,000, a 2% deductible is $9,000. Check your declarations page before you assume a roof claim is worth filing. See should I file a homeowners claim.
Example: one roof, three policies
Hail damages a 12-year-old asphalt roof on a home insured for $400,000. The roofer's replacement price is $22,000. The insurer applies 40% depreciation.
Under replacement cost coverage with a 1% wind and hail deductible of $4,000, the first check is $22,000 minus $8,800 depreciation minus $4,000, or $9,200. After the roof is replaced, the $8,800 depreciation is released, for $18,000 in total.
Under an actual cash value roof endorsement, the payment stops at $9,200.
Under a schedule that pays 60% at 12 years, the payment is $13,200 minus the $4,000 deductible, or $9,200 again in this case, with nothing more to come. These figures are illustrative. Your insurer's schedule, depreciation and deductible decide the real numbers.
What a complete roof estimate includes
An underpaid roof claim can come from an estimate that left items out. Compare the insurer's estimate with your roofer's for:
- Tear-off and disposal of every layer, plus the dumpster.
- Underlayment, ice and water barrier where code requires it, starter strips and ridge cap.
- Drip edge, flashing, pipe jacks and vents.
- Steep roof and high roof charges where they apply.
- Decking replacement when boards are damaged or code or the manufacturer requires it.
- Gutters, downspouts and skylights damaged in the same storm.
- Permits and code upgrades, up to the ordinance or law limit, which is 10% of the dwelling limit in the standard form.
- A general contractor's overhead and profit when several trades are needed. See overhead and profit.
Decking is a frequent fight. The Minnesota Supreme Court held in 2025, in Great Northwest Insurance v. Campbell, that a replacement cost policy had to pay for new sheathing where code and the shingle maker's instructions didn't allow installing over the existing boards.
Why roof checks come in low
- The insurer priced a repair of some slopes, not a full replacement. See how to get insurance to pay for a roof replacement.
- Depreciation is heavy, and the second check hasn't been requested.
- Measurements are off. Ask for the roof report the insurer used and compare squares and pitch.
- Code items, decking or overhead and profit are missing.
- A cosmetic damage exclusion was applied to dents in metal roofing or gutters. See cosmetic hail damage exclusions.
How averages compare
Triple-I, using ISO data, puts the average homeowners wind and hail claim at about $15,708 for 2020 to 2024, with wind and hail making up more than 39% of homeowners losses in every year of that period. Your claim depends on the size and pitch of your roof, the materials, and what else the storm hit.
Getting the rest of the money
- Tell the insurer in writing, within 180 days after the loss, that you intend to replace the roof.
- Sign a contract with a licensed roofer and keep the invoice.
- Send a supplement for anything found during tear-off, such as rotted or gapped decking, before the new roof covers it up. See claim supplements.
- Send the final invoice and photos of the finished roof to release the depreciation. See how long a roof insurance claim takes for typical timing.
- Watch the checks. Your mortgage company may be named and need to endorse them.
Common questions
Does insurance pay the full cost of a new roof?
Under replacement cost coverage, it pays the full cost of a like-kind roof minus the deductible, in two stages. Under an actual cash value endorsement or roof schedule, it pays less.
How is roof depreciation calculated?
Insurers may base it on age compared with expected life, adjusted for condition. Ask the insurer for the age and life expectancy it used.
Will insurance pay for an upgraded roof?
It pays for like kind and quality, plus code-required items up to the ordinance or law limit. You pay the difference for an upgrade by choice.
Can I keep the insurance money and not replace the roof?
Under a replacement cost policy, you can keep the actual cash value payment, but you won't receive the withheld depreciation without completing the replacement. Your mortgage company may also have a say.
Roof payout lower than the roofer's bid?
ClaimWarriors compares the insurer's roof estimate line by line and negotiates the difference. See our roof damage claim services or contact us for a free claim review.
This article is general information, not legal advice. Payouts depend on your policy, endorsements and state law. Last reviewed November 2026.